You handle a sibling who borrows money and never repays by doing four things in order: stop all new lending, work out the exact balance from your own records, state that balance and a deadline in one calm conversation, and put any repayment plan in writing with consequences. Some loans you will collect. Some you will not, and you get to decide which ones are worth chasing.
If you have been avoiding this for months, that avoidance is normal. Most people are not sitting on the money. They are sitting on a mix of resentment, guilt, obligation and plain exhaustion, and none of those feelings make for a useful opening line.
Here is the good news from my side of it: the conversation you are dreading takes about fifteen minutes, and it goes considerably better when you walk in with a number, a date, and a script. This guide walks through the whole sequence, updated for 2026, from figuring out what is really owed to deciding when to stop.
Table of Contents
- What You Need
- Step-by-Step: How to Handle a Sibling Who Borrows Money and Never Repays
- 1. Separate a one-time difficulty from an ongoing pattern
- 2. Confirm exactly how much is owed
- 3. Decide the outcome you can actually enforce
- 4. Have a direct conversation about the debt
- 5. Put the agreement and deadline in writing
- 6. Set consequences you can carry out
- 7. Protect your money and review next steps
- Common Mistakes
- Frequently Asked Questions
- Should I write off money my sibling borrowed?
- How do I ask a sibling to repay money I lent?
- What if my sibling keeps borrowing but promises to pay later?
- Should I tell other family members about the unpaid loan?
- When is small claims court worth it for money owed by a sibling?
- What to Do First
What You Need
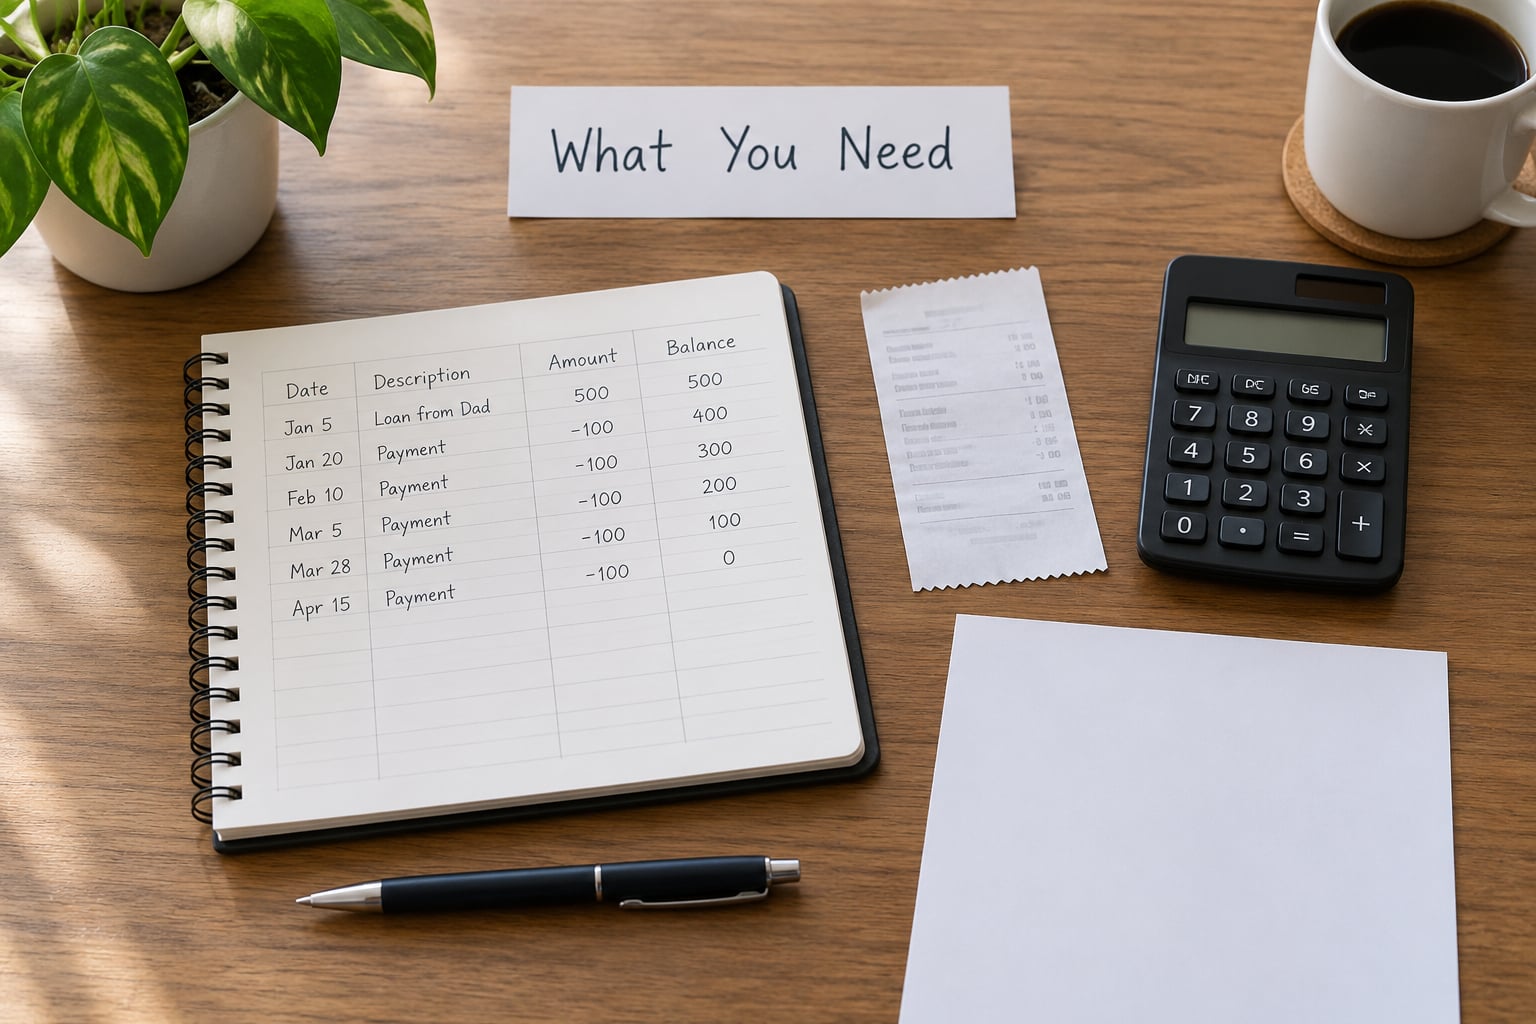
Five things, and you can gather all of them in an hour. Going in without them is what turns a conversation into a fight.
- Proof of the loan. Bank statements, Zelle or Venmo records, cash app histories, texts where the money was discussed, receipts for anything you paid directly. Screenshots and dates matter more than you would think.
- A calculated balance. Principal, anything you agreed to, repayments already made, and what remains. A round number you can say out loud lands better than a vague estimate.
- Any written terms. A text thread, a note, an email, even a memo you wrote the same day. If nothing exists, write down what you remember now while it is still accurate.
- A firm repayment boundary. A date, not a mood. “By the end of the month” is enforceable in your head; a specific calendar date is enforceable in reality.
- An outcome you can live with. Decide in advance what you will accept, including partial payment or writing it off, so the conversation has a floor you already chose rather than one you choose under pressure.
Step-by-Step: How to Handle a Sibling Who Borrows Money and Never Repays
1. Separate a one-time difficulty from an ongoing pattern
The difference between someone who cannot pay and someone who will not pay changes everything about what you do next. Take an honest look at which column your sibling is in.
| What you see | Likely reading | Right response |
|---|---|---|
| A real crisis: job loss, medical bills, a funeral | Genuine hardship | Offer a small schedule, and consider paying a vendor directly rather than handing over cash |
| A vague story with no dates, repeated across years | Avoidance | Ask for a number and a date, then hold them to it |
| Works, buys things, changes the subject when money comes up | Choice | Stop lending, state the balance once, set a deadline |
| Promises repay next week, for three years running | The promise is the product | Assume nothing without a written plan and a start date |
| Asks again before finishing the last loan | A pattern, not an emergency | Decline the new request in writing, same day |
One honest test: if your sibling were repaying, would you already know what the next three months look like? If the answer is no, treat this as a pattern, and stop treating each new request as an exception.
2. Confirm exactly how much is owed
Build the number yourself, from records, not from memory. Start with the date and amount of each transfer. Subtract anything they have sent back, including small amounts that felt like gestures rather than repayments.
Then decide about interest. If you never discussed it, do not suddenly introduce a rate at the conversation. It reads as an ambush and it turns a money talk into an argument about fairness.
Keep your working notes somewhere they will survive. A plain spreadsheet, a note in your banking app, a dated page in a notebook. This is what you would rely on if the conversation ever goes sideways.
3. Decide the outcome you can actually enforce
Enforceable is the word doing the work here. Pick the option you could carry out yourself, without a lawyer, without your parents, without anyone being angry on your behalf.
- Full repayment plan: the whole balance over a schedule they proposed and you approved. Best when their income is stable and the number is large.
- Partial settlement: one payment of less than the full amount to close the file. Often the fastest route to actually getting something.
- Fixed final payment: one amount, one date, done. Useful when the original amount stretched and nobody remembers the terms.
- Write-off: you accept the loss and say so out loud, which is the only way the resentment actually clears.
Write the outcome you picked on the same page as the balance. You will be tempted to soften it, and that is exactly when having it in writing pays off.
4. Have a direct conversation about the debt
Private, unhurried, and not in front of anybody else. A car, a walk, a phone call where neither of you is driving. Text works too, and it gives you a record, but it removes tone, and tone is doing a lot of work in a sibling conversation.
Say the amount and the date first. Then ask a question and stop talking. The silence is uncomfortable and it is also where the real answer comes out.
Hey, I want to talk about the money I sent you. Looking at my records, I have given you a total of [amount] since [date], and I have received [amount] back, which leaves [balance] outstanding. That has been outstanding for [length of time]. I am not trying to fight about the past. I need to know what you can do about it and by when. What is realistic for you?
Three rules for the whole exchange. Stay on facts rather than character. Do not list old grievances to win the current point. And do not apologize for wanting your money, because guilt is the single most common reason a sibling walk backs out of a fair agreement ten minutes later.
If they cry, if they get angry, or if they accuse you of humiliating them, do not fill the silence with reassurance. Say: “I hear you, and my answer about the money is still the same. I would rather do this than keep losing sleep over it.”
5. Put the agreement and deadline in writing
One page, plain language, no lawyer required. A private arrangement between siblings is much easier to work with when everyone can see the same terms.
- The exact amount and what it covers
- The schedule: amount and date of each payment
- The final payment date
- How payments will be made, and to whom
- What happens if a payment is missed
- A signature line for both of you, and a date
Send it neutrally. Something like: “Here is what we talked about. I wrote it up so neither of us has to remember all the details. If it looks right, sign and send it back.” A plain document is easier to sign than a conversation you both have to keep having.
Then read the response, not just for agreement, but for signal. “That looks reasonable, let me check a couple of things” is a constructive answer. Silence, a rewrite that removes the deadline, or a message about how you are making them feel is an evasive one, and evasive answers tell you what kind of plan to expect.
6. Set consequences you can carry out
A consequence you will not follow is worse than no consequence at all. Choose yours before you announce them, and keep them proportionate.
- No new money, ever, until the balance is cleared. This is the one that stops a pattern fastest.
- Everything in writing. Future money conversations happen by text or email so there is a record.
- One missed payment moves the whole balance to the final date. Stated in the agreement in advance.
- A defined cooling-off. You stop discussing the money for a set period while the sibling keeps making payments on schedule.
- Pay the vendor directly. If they owe for rent, a utility, or a medical bill, some institutions will take payment from you directly. It removes the chance of the money disappearing into a different problem.
- Ending the arrangement. For some people the real consequence is telling the sibling the loan is closed and the relationship continues without money in it.
7. Protect your money and review next steps
Track what lands. A simple monthly check against the agreement keeps it real and keeps you from re-opening the conversation every time you feel anxious about it.
Two terms worth knowing, both general and both worth confirming locally. An IOU is a signed note that states someone owes you an amount. A promissory note goes further: it typically states the amount, a repayment date and sometimes interest, which is what makes it more useful as evidence. The statute of limitations is the window after which you generally cannot bring a claim; how long that window runs for an unpaid family loan varies by state and by the type of claim, so confirm yours rather than assume.
Small claims court is a real option in most places for smaller amounts, and it is usually a bad one for sibling debts under a few thousand dollars once you add filing fees, missed work, serving papers, and the permanent damage to the relationship. Before you consider it, ask a local attorney or your county court’s self-help center what the process and cost look like where you live. Nothing here is individual legal advice, and rules differ by state.
Red flags that mean it is time to stop checking in and start protecting yourself: they ask for a new loan before making the first payment, they block your number after a reminder, they acknowledge the debt in writing and then stop, or they ask you to sign something vague that would erase your claim.
And if the money was handed over in cash years ago with no record at all, be honest with yourself about how recoverable it is. Write down what you remember, keep it, and treat the outcome as uncertain. The note still matters even if it is not litigation.
Common Mistakes
Most of the damage in these situations comes from a short list of avoidable moves. Each one has a straightforward fix.
- Lending without ever defining the terms. Fix: say out loud what you expect and when, in the first conversation, even if it feels cold. Warmth does not require ambiguity.
- Making the ask in front of relatives. Fix: always private first. Family group chats turn a debt into a court of opinion, and you lose control of the conversation.
- Treating promises as payments. Fix: a promise counts when it comes with an amount, a date and a written record. Anything else is a wish.
- Setting a schedule you wish you could afford yourself. Fix: ask them to propose the schedule. People commit to plans they designed, not plans you imposed.
- Paying late fees on their behalf, repeatedly. Fix: stop absorbing the cost. If you are covering the consequences of a missed payment, you have become the lender of record on a loan you did not agree to.
- Quietly reclassifying the loan as a gift. Fix: make it explicit. “I am writing this off” is a decision you can move past. A loan you simply stop mentioning becomes resentment with no ending.
Three boundary tips to keep. Decline the next request the same day, in writing, so you are not deciding in the moment while they are standing there. Do not use labels like mooch or deadbeat, because labels give them something to argue about instead of the balance. And tell your partner or a person you trust what is happening, because this affects your household too and secrets have a way of becoming arguments later.
Frequently Asked Questions
Should I write off money my sibling borrowed?
You can forgive the balance, but only after deciding what forgiveness means and telling your sibling clearly. If the money would have mattered to you financially, converting it to a gift may preserve the relationship and end the resentment. If you forgive it silently and they ask again, you have taught them that asking works. Either way, write down that the balance is closed so you are not still carrying it.
How do I ask a sibling to repay money I lent?
Pick a private, calm moment and state three things: the amount, the relevant dates, and what you are proposing. Ask how they will repay rather than leading with why they have not already. Then let them answer without interrupting. Close by agreeing on the next step in writing. The conversation goes better when it sounds like administration, not an accusation.
What if my sibling keeps borrowing but promises to pay later?
A promise is not a plan. Do not send more money until the existing balance has a clear amount, a deadline and a record of payments. If they ask again, say no in writing and reference the plan: nothing new until the current one is on track. People who will not repay rarely start repaying because they promised to.
Should I tell other family members about the unpaid loan?
Keep it between you unless there is a real risk of fraud, coercion, or financial exploitation, or unless family members are being asked for money to cover the same gap. Telling everyone usually produces opinions rather than payments and can permanently split the family. If you do loop someone in, tell them your plan and your limit before they hear your sibling’s version.
When is small claims court worth it for money owed by a sibling?
Rarely, and almost never for small amounts. Filing fees, serving papers, time off work, and the permanent damage to the relationship usually cost more than the balance. It makes more sense for a larger sum where you have bank records or a signed note. Rules on limits, deadlines and evidence vary by state, so check with your county court self-help center or a local attorney before filing anything.
What to Do First
Verify the balance today, from your own records rather than from a feeling. Then choose the outcome you can enforce, and write it down before you feel any pressure to soften it.
Say the number and the date in one calm, private conversation, and put whatever you agree in writing on a single page. From that day forward, the answer to a new request is no until the old one is handled. That is how you stop being the family member who always absorbs it.