A weekly money review takes ten minutes: open your accounts, see where you stand, scan the last seven days of spending, confirm what is due next, and pick one action for the week ahead. Ten minutes once a week is enough, because the job of the review is timing rather than accounting. Catch a drifting budget while it is still a seven-day problem and the fix stays small.
Pick a day and a time, set a timer, and do not extend it. Most people quit money systems because they turn them into a project. A short slot you actually keep beats a thorough one you abandon by week three.
Table of Contents
- What You Need
- Step-by-Step: How to Do a Weekly Money Review in 10 Minutes
- Step 1: Check Your Current Cash Position (0-2 minutes)
- Step 2: Scan Spending Since the Last Review (2-5 minutes)
- Step 3: Compare Spending With Your Plan (5-7 minutes)
- Step 4: Check Upcoming Bills and Payments (7-9 minutes)
- Step 5: Choose One Money Action for the Week — the Point of the Weekly Money Review
- Common Mistakes That Break the Ten-Minute Review
- Frequently Asked Questions
- How often should I do a weekly money review?
- What should I review first during a 10-minute money check?
- How do I do a weekly money review when my income is irregular?
- Should I review my budget or my bank accounts first?
- What if I find a spending mistake during the review?
- Is a 10-minute money review enough to stay on track?
- Conclusion
What You Need
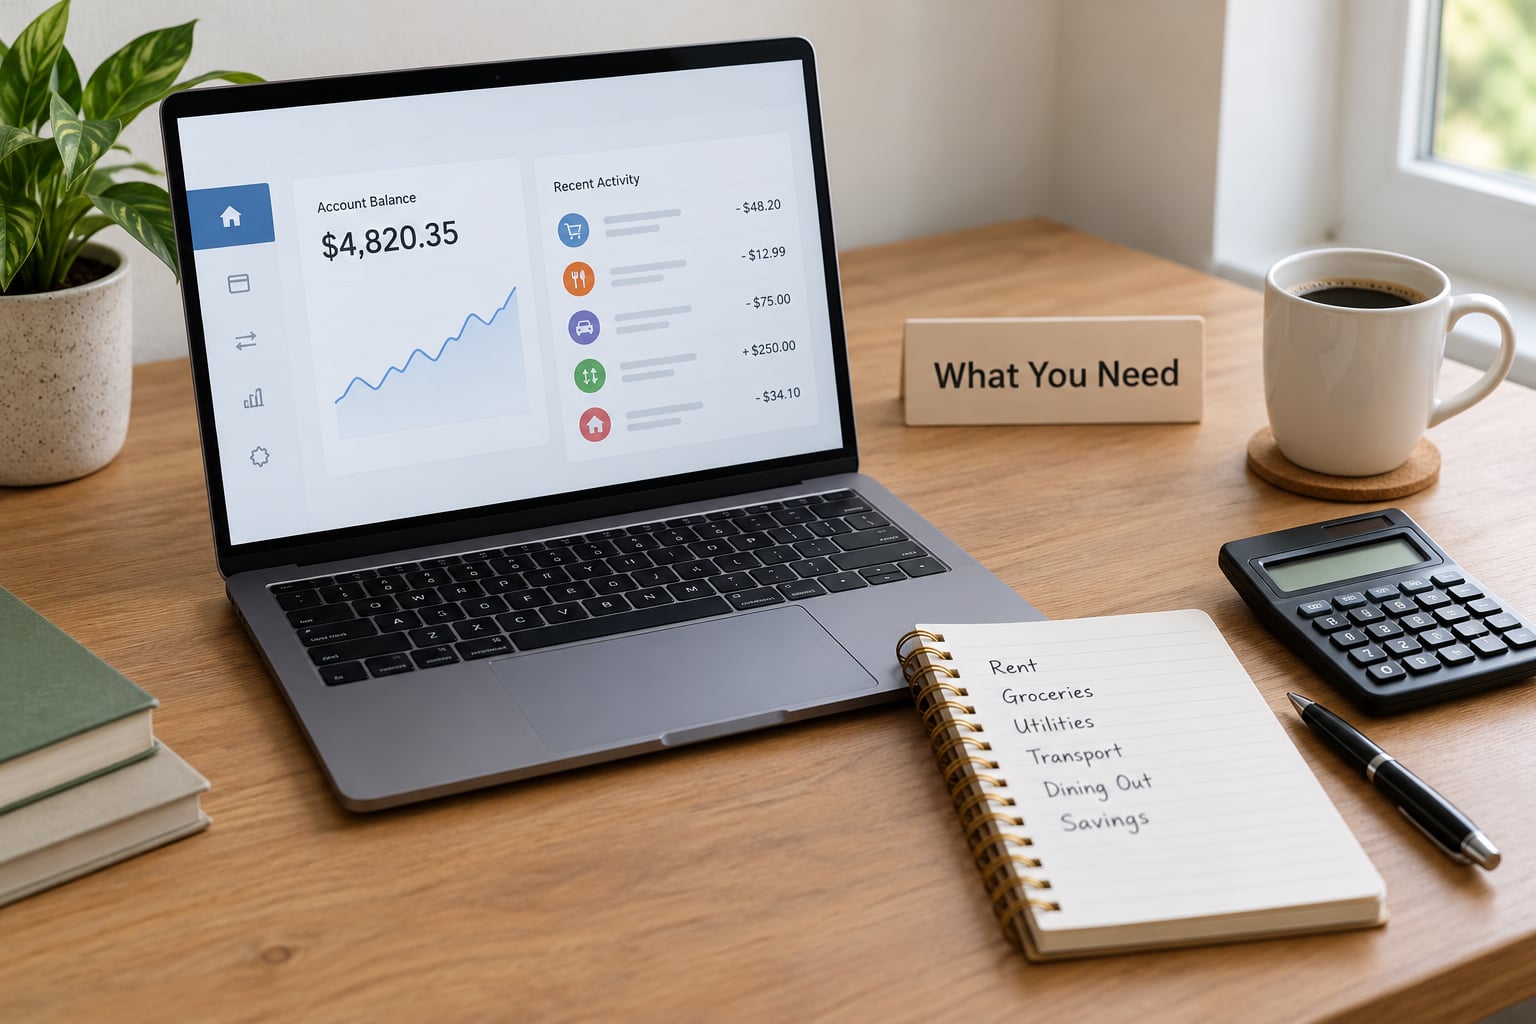
Four things, and any screen can hold all of them: your account balances, the transactions from the past seven days, a list of what is due in the next seven days, and one place to write down a single decision.
Most banking apps show balances and recent charges in the same view, so you can do the whole review without switching between tools. If your accounts are spread across several institutions, open each tab before you start rather than during the review.
If you track nothing right now, keep a note on your phone with five empty lines. Building the habit first and adding categories later works far better than setting up a perfect system you never start.
Step-by-Step: How to Do a Weekly Money Review in 10 Minutes
The agenda below is built on a hard ten-minute cap, with each block given a fixed share of the time. The time box is the whole trick, because it stops the review from turning into an audit of your life choices.
Step 1: Check Your Current Cash Position (0-2 minutes)
Open every account and write down three numbers: what you can spend freely right now, what is already committed, and what is owed. Add your credit card total to the last number, since a card balance is a bill with a due date that people routinely forget.
If available cash cannot cover what is due before the next payday, stop and deal with it now. Everything else in the review is optional when the next seven days are not covered.
Step 2: Scan Spending Since the Last Review (2-5 minutes)
Scroll the last seven days of transactions and sort them into four or five broad buckets, such as groceries, fuel, eating out, subscriptions, and household. Broad is fine. The goal is to see the pattern, not to build a ledger you will never update again.
Flag anything you do not recognize. A charge you cannot place is either a duplicate, a forgotten trial that converted, or fraud, and all three are far cheaper to fix today than in three weeks.
This is also the natural moment for a quick subscription audit. Cancel one recurring charge you have not used in the last month. One cancellation a week quietly reallocates more money than most budgeting arguments ever do.
Step 3: Compare Spending With Your Plan (5-7 minutes)
Work out your weekly flexible spending figure and compare it with what you actually spent. If you budget monthly, divide the flexible amount by four to get a weekly number. A weekly figure reads better than a monthly total with no edges, and it is far easier to judge.
Find the single largest variance between plan and actual. Usually one category explains nearly all of it. A week where eating out ran over is a two-minute adjustment; a month of drift is demoralizing and is where most reviews get abandoned.
Step 4: Check Upcoming Bills and Payments (7-9 minutes)
Look at the next seven days: rent or mortgage, utilities, subscriptions, loan payments, and any automatic transfer between your accounts. Confirm the money is actually there for each one before its due date.
Check scheduled transfers while you are there. A savings transfer that quietly failed three weeks running is a common find, and moving money on the same day you look is how you fix it.
Step 5: Choose One Money Action for the Week — the Point of the Weekly Money Review
End with a decision, not a feeling. Good options: move a set amount to savings on payday, trim one category for the remainder of the week, schedule an automatic bill payment, or pay down a balance above zero.
One action is enough, and it should be specific enough to do today. Write it in the same note where you keep your balances. A review with no recorded decision becomes a review you are still deciding whether to do.
Common Mistakes That Break the Ten-Minute Review
Reviewing every transaction turns ten minutes into forty and guarantees a skip next week. Scan, group, and move on. Six or seven days of spending usually reveal the pattern without you reading a single line twice.
Mixing fixed bills with discretionary spending makes a budget impossible to judge. Keep bills in one group, spending money in another, and savings in a third. When those three numbers blur together, the overspend has no obvious cause.
Forgetting to check transfers is the most common blind spot. Bills, savings moves, and investment contributions should all be on a written schedule you glance at every week.
Reacting emotionally to one unusual purchase turns the review into a source of guilt. Correct the single action, then let it go. Reviewing weekly shrinks every decision to something small enough to fix, which is exactly why the weekly cadence works where the monthly one stalls.
Avoiding the review because the numbers scare you is the failure mode the ten-minute cap exists to beat. Most people find that opening the accounts becomes about as ordinary as checking the weather after a few weeks of showing up.
Frequently Asked Questions
How often should I do a weekly money review?
Once a week, on the same day, is the useful answer. Weekly works because a problem you find in seven days is still small enough to correct. Monthly reviews arrive after most of the damage is done, and daily checking tends to turn into anxious account watching. Pick a slot you can protect, like Sunday evening or Monday morning before the week fills up, and treat a missed week as a reason to resume rather than a reason to quit entirely.
What should I review first during a 10-minute money check?
Balances first, always. Before anything else, confirm the money you can spend today and the money you owe before the next payday. That takes about two minutes and tells you whether the rest of the review is about fine-tuning or about covering a gap. If there is a gap, the review changes shape: bills and transfers come before spending categories, and the flexible budget for the week simply gets smaller until the gap closes.
How do I do a weekly money review when my income is irregular?
Replace a weekly target with a rolling four-week average of what you actually earned. Divide that by four to get a weekly spending figure, then pay yourself first out of each payment as it lands. Review what is due across the whole month rather than the next seven days, since a quiet month still has bills. Many freelancers and contractors also keep a sinking fund, a separate pot you refill so irregular bills do not wreck a good month.
Should I review my budget or my bank accounts first?
Accounts first, always. The budget is a plan written by an earlier version of you, and the accounts are what actually happened. Reading accounts first keeps the review grounded and takes two minutes. After that, compare actual spending with the plan and look for the biggest gap. A monthly budget that has drifted is a useful thing to correct, but a budget reviewed before you check what is really in the account can hide a missed bill or a failed transfer.
What if I find a spending mistake during the review?
Correct the money and record the cause, then move on. If the charge is unfamiliar, call your bank or card issuer before it posts further; disputed charges are far easier to handle the same week. For an overspend, cut one category for the rest of the week rather than trying to claw everything back at once. The mistake is rarely the cost. It is the pattern, and the review is where the pattern becomes visible.
Is a 10-minute money review enough to stay on track?
For staying on top of things, yes. Ten minutes a week catches low balances, unfamiliar charges, failed transfers, and drift in your spending before any of them compound into a month-end surprise. It is not a deep audit, and it is not meant to be. Pair it with a longer monthly look at categories, subscriptions, and debt progress, and you have a complete rhythm without asking one session to do both jobs.
Conclusion
A weekly money review in ten minutes comes down to three things: check where you stand, confirm what is due in the next seven days, and leave with one action written down. That is the entire habit, and it works because the decision stays small enough to actually make.
Start today with the first step. Open your accounts, note the balances and what is owed, and set a recurring ten-minute slot this week. 2026
Money rules, rates, and account features differ by country and by bank, and this is general information rather than advice for your situation. A qualified financial planner or your bank’s own tools can answer questions specific to your accounts.